

SoLo Funds: Lend & Borrow

- 5.63K Reviews
- 4.6
- Downloads
- 500,000+
Our take on SoLo Funds: Lend & Borrow from Appgk
When an unexpected bill lands before payday, the usual choices are not very appealing: ask someone you know, use a conventional credit product, or simply wait and hope the timing works out. SoLo Funds: Lend & Borrow takes a different approach by putting short-term borrowing and lending in the same finance app. Its central idea is simple: a member can request money on their own terms, while another member can choose to lend and potentially benefit from doing so.
I find that focus more interesting than the typical “instant cash” pitch because it makes the user think about both sides of the transaction. This is not just an app I would open casually to browse financial tools. It is designed around a specific moment: needing a relatively small amount of help for a short period, or having money available that I may want to lend through the platform. That narrow purpose is also its biggest strength and its most important limitation.
SoLo Funds is a free finance app from Solo Funds, available for Everyone and compatible with Android 8.0 or later. It was released on October 22, 2021, and the current version is 2.19.0. The app has reached over 500 thousand installs, with a 4.6 average from around 25 thousand ratings and roughly 5.6 thousand written reviews. Those figures suggest that the concept has attracted a substantial user base, but they do not remove the need to understand how the model fits your own situation.
Borrowing and lending are treated as two sides of one decision
The capability I kept coming back to is the app’s peer-to-peer structure. Instead of presenting borrowing as a one-way service from a financial company, SoLo Funds connects a person asking for help with people willing to fund requests. The practical effect is that the borrower is not only choosing an amount; they are entering a community marketplace where the request needs to make sense to someone on the other side.
Best Parts of SoLo Funds: Lend & Borrow
Things to Keep in Mind About SoLo Funds: Lend & Borrow
That changes the mindset. With a familiar bank or credit card, the process is usually built around a fixed product, an approval decision, and terms determined largely in advance. Here, the experience is more personal and more dependent on the availability and choices of other users. The store summary captures that philosophy with the idea of borrowing on your own terms and lending to reap the benefits, but the real-world implication is that flexibility comes with uncertainty.
For a borrower, the appeal is obvious. A timing problem can be different from a long-term affordability problem. If a paycheck is due soon but a necessary expense arrives first, a short-term solution may feel more suitable than opening a larger line of credit. For a lender, the attraction is the opportunity to put idle money to work through individual requests rather than leaving it untouched. Neither use is automatically wise, though. The app can organize a transaction, but it cannot turn an unaffordable repayment into an affordable one.
News and Features Related to SoLo Funds: Lend & Borrow

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
I would therefore treat the core feature as a planning tool, not emergency permission to spend. Before requesting money, I would write down the exact amount needed, the date on which repayment should be realistic, and what happens if income arrives late. That small exercise is especially important here because the app’s flexibility can make a request feel easier than the repayment decision that follows.
What the experience feels like for a borrower
In practice, a borrower needs to be clear and disciplined. The useful part of the model is being able to frame a request around a real short-term need instead of accepting a generic loan product. The uncomfortable part is that the request depends on another person deciding it is worth supporting. A request can be financially sensible and still not receive the response you hoped for at the moment you need it.
Don't want to read the full review?
That makes timing a meaningful factor. If I were using the app for a utility bill, a prescription, or a necessary trip to work, I would not wait until the last possible minute. I would prepare the request before the expense becomes urgent and keep a backup plan ready. A peer-to-peer marketplace is not the same as holding a guaranteed credit facility, so anyone who needs certainty at a specific hour should be careful about relying on it as the only option.
The app’s strongest psychological benefit is that it can make the borrowing purpose feel more deliberate. Instead of taking a larger amount because it is available, I can focus on the gap in front of me. That can reduce unnecessary borrowing when the user is honest about the need. On the other hand, the community format may encourage optimism: seeing that other people lend can create the impression that a request will always be covered. I would not make a financial commitment on that assumption.
Screenshots
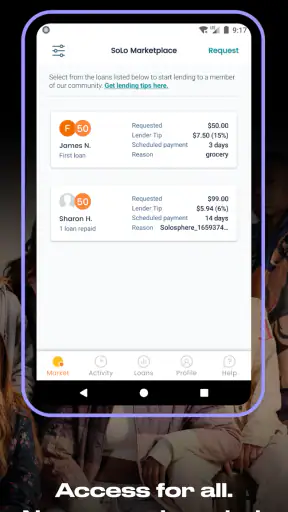
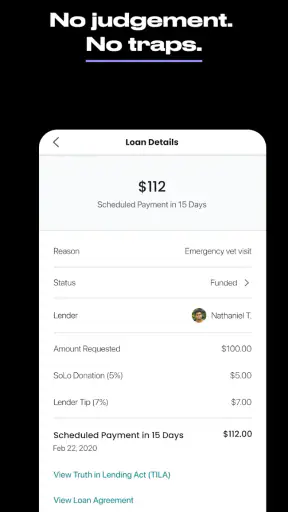
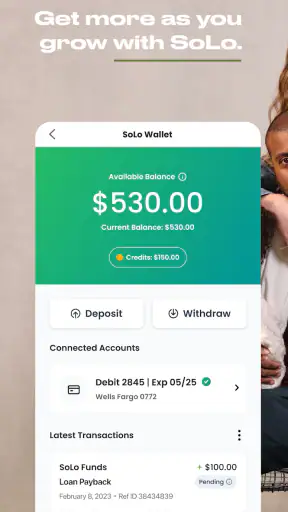
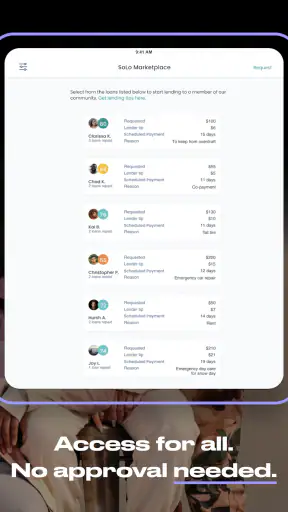
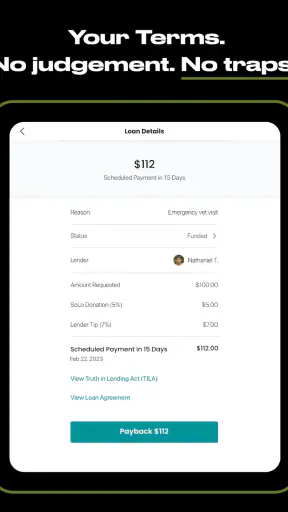
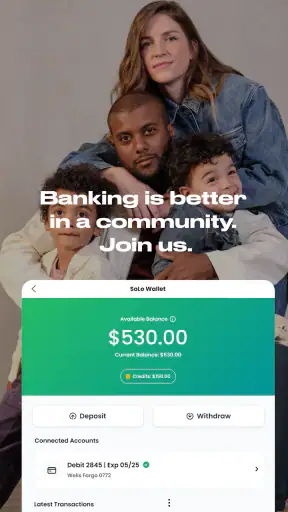
Another practical question is whether this is suitable for building a regular spending habit. In my view, it is not. Repeatedly using short-term borrowing to cover ordinary living costs points to a budget problem that an app cannot solve. SoLo Funds makes more sense as an occasional bridge than as a replacement for an emergency fund, stable income, or a carefully managed credit arrangement.
What the experience feels like for a lender
The lending side requires a different kind of attention. A person considering a request is not simply choosing an investment fund from a menu. They are deciding whether to place money behind an individual’s short-term need, which means the decision carries a human element as well as a financial one. That may appeal to users who prefer a direct sense of where their money is going, but it also means the lender should avoid treating every request as equally suitable.
My practical rule would be to lend only money I could leave unavailable without affecting rent, food, transport, or bills. The possibility of benefiting from lending is not a substitute for liquidity. I would also spread decisions across a personal budget rather than putting a large share of available cash into one request. This is one of the less obvious trade-offs of the app: the feature can feel more engaging than a conventional savings option, but engagement should not be confused with safety or guaranteed access to funds.
The lender side may also suit someone who values choosing selectively. Instead of automatically committing, the user can think about the request, the amount, and whether the timing fits their own finances. That control is useful, but it creates responsibility. If I were lending, I would keep a simple record of what I had committed and when I expected the money to become available again. The app may show the transaction, but my own cash-flow plan should remain the final authority.
A realistic everyday use case
Imagine that I have a necessary car repair during the week, my paycheck is several days away, and the repair cannot reasonably wait. I calculate the smallest amount that would solve the problem rather than requesting extra money for unrelated purchases. I check whether repayment will still leave enough for groceries and transport, then submit a focused request. If the request is supported, the app has helped bridge a specific timing gap without forcing me into a larger, longer-term product.
That example shows where the capability can be genuinely useful: the expense is important, the amount is limited, and the repayment plan is tied to a known change in cash flow. I would still keep a second option in mind, such as speaking with the service provider about timing or asking a trusted person directly. The point is not that SoLo Funds replaces every other solution; it gives me another route when the circumstances fit.
Now change the situation slightly. Suppose I am already behind on several bills, have no reliable income date, and need to borrow again to repay an earlier obligation. The same feature becomes much less attractive. A peer-to-peer request may postpone the pressure without improving the underlying position. In that case, I would look for budgeting help, contact creditors, or seek a longer-term solution instead of adding another short-term commitment.
For a lender, the matching scenario might be having a modest amount of spare cash that is not needed for upcoming essentials. I could review requests during a calm moment, decide on a limit I am comfortable with, and avoid making a rushed decision because a story feels emotionally compelling. The non-obvious lesson is that the app’s social design can be both its appeal and its risk: empathy may encourage generosity, but financial decisions still need boundaries.
Where it differs from ordinary alternatives
Compared with a credit card, SoLo Funds is more focused on a defined short-term request and a peer-supported transaction rather than an ongoing revolving balance. That can be helpful for someone who wants to avoid carrying a broad spending facility. A credit card may be more convenient for an immediate purchase because acceptance is already built into the payment process, while SoLo Funds is better understood as a separate borrowing workflow.
Compared with a conventional personal loan, the app feels narrower and potentially more flexible, but it may not offer the same sense of predictability that comes with a fixed application and scheduled structure. A traditional loan can be a better fit for a large, planned expense that needs stable terms over a longer period. Using a short-term peer-based option for that kind of need would be a mismatch.
Compared with asking family or friends, SoLo Funds creates distance and structure. That may spare someone an awkward personal conversation, and it gives lenders a way to participate without being part of the borrower’s private circle. Yet the emotional cost does not disappear; it is simply moved into a digital marketplace. I would still approach the request with the same honesty and restraint I would use when asking someone I know.
Compared with keeping an emergency fund, the app is a fallback rather than a replacement. Savings provide more control because the money is already yours and there is no new repayment obligation. If I had enough savings to cover the expense, I would generally prefer using them, provided doing so would not leave me exposed to the next emergency. SoLo Funds becomes more relevant when the problem is temporary timing and my own reserves are not enough.
The trade-offs that matter before signing up
The first trade-off is flexibility versus certainty. The ability to request or consider a loan on personal terms sounds empowering, but the result depends on participation from other users. I would not use it for a deadline where failure would cause immediate serious consequences unless I had a dependable backup.
The second is access versus repayment pressure. A short-term solution can be less burdensome than a large credit product when used carefully, but it still creates a future obligation. The correct question is not only “Can I get this money?” but “Will repaying it leave my next pay period workable?” That distinction separates a useful bridge from a cycle of repeated borrowing.
The third is community participation versus financial distance. Some users may appreciate lending directly to people with immediate needs. Others may prefer the clearer boundaries of a bank account or a traditional financial product. Neither preference is wrong. I would skip the lending side if I found myself making decisions mainly from urgency or sympathy rather than from a controlled budget.
There is also a practical learning curve. Anyone unfamiliar with peer-to-peer finance should read each screen carefully, understand the obligation before accepting money, and keep personal records. I would avoid clicking through quickly simply because the situation feels urgent. A free download does not mean the financial decision itself is cost-free, and the app should not be judged only by how easy it is to install.
Who is most likely to benefit
SoLo Funds is most compelling for people who occasionally experience a short gap between a necessary expense and incoming income, and who can identify a credible repayment point. It may also suit financially organized users who want to consider lending selectively and can afford to keep committed money out of their immediate spending plan.
I would be more cautious if someone has irregular income, no emergency buffer, or a history of borrowing to cover previous borrowing. The app may still appear attractive in that situation, but the central capability is not designed to repair unstable cash flow by itself. Someone who needs a predictable, larger loan, a long repayment period, or guaranteed payment access may be better served by comparing conventional options with clear written terms.
The Everyone age rating makes the app broadly accessible from a content perspective, but financial responsibility is still the real threshold. Younger or inexperienced users should involve a trusted adult or adviser before making commitments they do not fully understand. The absence of complicated language in an app would not make the underlying obligation simple.
On the technical side, Android users should note that the app requires Android 8.0 or later. I appreciate that the current version is identified as 2.19.0 because it gives users a clear compatibility checkpoint before installing. The app is free to download, but I would never interpret that as a promise that borrowing or lending has no financial consequences; the important details are the terms attached to the transaction itself.
My recommendation after weighing the capability
I see SoLo Funds as a focused tool rather than a complete personal-finance system. Its best idea is the connection between a borrower who needs a short-term bridge and a lender who is willing to consider that request. When the need is specific, the repayment plan is realistic, and the user has a backup, that structure can feel more human and more controlled than reaching immediately for a broad credit product.
My advice would be to install it only with a clear purpose. Borrow the smallest amount that solves the actual problem, decide how repayment fits into the next budget before accepting anything, and do not treat a successful request as evidence that future requests will be available. If lending, use money that is genuinely spare and set a personal limit before emotion enters the decision.
Overall, I would recommend SoLo Funds to a careful user facing an occasional timing problem, and to a lender who understands that participation requires patience and financial discipline. I would not recommend making it the foundation of a monthly budget or using it when repayment is uncertain. The app’s value comes from its narrow capability; respecting that boundary is what makes the experience useful rather than risky.
SoLo Funds: Lend & Borrow FAQ
What is SoLo Funds: Lend & Borrow, and how does it work?
SoLo Funds is a community-based financial platform designed to help members request or provide small, short-term loans. A borrower creates a request, explains the amount needed, and proposes an optional tip for the lender. Other members can review the request and choose whether to fund it. The service is not the same as a traditional bank loan, and availability, terms, and approval depend on the platform and user activity.
Can anyone borrow money through SoLo Funds?
Not necessarily. Users generally need to meet SoLo Funds’ eligibility requirements, complete account verification, and provide the requested personal or financial information before accessing borrowing features. Approval is not guaranteed, and available amounts may depend on account history, repayment behavior, location, and current platform rules. Before submitting a request, review the app’s eligibility conditions carefully because requirements may change over time.
How much does borrowing through SoLo Funds cost?
Borrowing costs can include an optional tip to the lender and, depending on the circumstances, possible platform, processing, late, or other applicable fees. The exact amount should be displayed during the request and repayment process. Since pricing and policies may change, users should read the current fee disclosures rather than relying on older reviews. Always check the total repayment amount before accepting a loan.
What happens if I cannot repay a SoLo Funds loan on time?
Missing a repayment deadline may result in late charges, collection activity, restrictions on using the platform, or other consequences described in SoLo Funds’ current terms. It could also affect your ability to borrow in the future. If you expect difficulty repaying, contact support as soon as possible and review the available options. Do not request a loan unless you have a realistic plan to repay it on schedule.
Is SoLo Funds safe and legitimate to use?
SoLo Funds uses account controls, identity verification, payment processing, and platform rules intended to support lending between members, but no financial app is completely risk-free. Users should protect login details, enable available security features, and communicate only through approved channels. Before depositing money or requesting funds, read the privacy policy, lending terms, fee information, and dispute procedures so you understand the risks and responsibilities.











